For anyone searching “belasting freelancer België”, the short answer is this: a Belgian freelancer working as a sole proprietor often keeps roughly 50% to 65% of business revenue after professional expenses, social-security contributions and personal income tax. The exact result depends on your profit, deductions, municipality, family situation and whether you operate through a company.
This guide explains the Belgian freelancer tax burden using the latest published 2026 tax brackets and social-contribution rules. Amounts are illustrative, not a personal tax assessment.
How freelancer taxation works in Belgium
A freelancer usually operates either:
- As a sole proprietor (eenmanszaak/entreprise individuelle)
- Through a company, commonly an SRL/BV
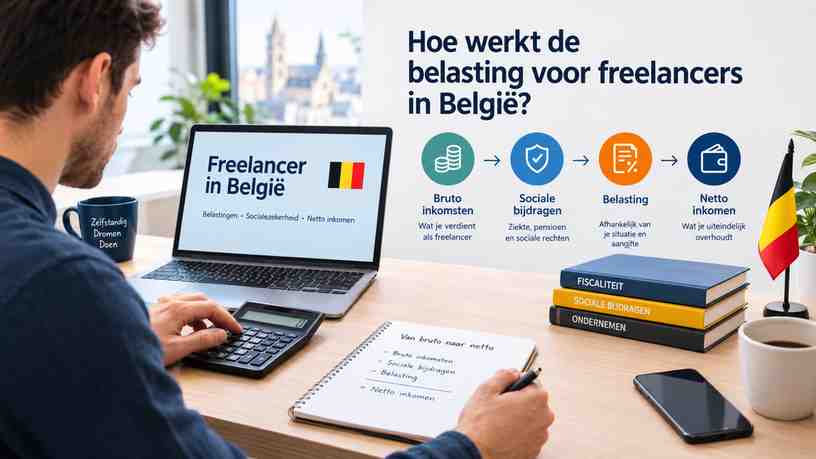
With a sole proprietorship, your business profit is taxed directly as personal professional income. The basic calculation is:
Business revenue – deductible professional expenses = net professional income
You then pay:
- Social-security contributions
- Progressive personal income tax
- A municipal surcharge on the personal income tax
- VAT administration, where applicable
VAT collected from customers is not your income. You normally hold it temporarily and remit it to the tax authorities, after deducting eligible input VAT.
Belgian income-tax brackets for 2026
For income year 2026 (assessment year 2027), Belgium applies progressive rates to taxable income:
| Taxable income band | Federal rate |
|---|---|
| €0–€16,720 | 25% |
| €16,720–€29,510 | 40% |
| €29,510–€51,070 | 45% |
| Above €51,070 | 50% |
These brackets come from the Belgian FPS Finance tax-rate table.
The highest rate is not applied to your entire income. Only the portion inside each band is taxed at that rate. Belgium also grants a basic personal tax allowance of €11,180 for income year 2026. This allowance can increase if you have dependent children or other qualifying circumstances.
A non-resident may not always receive the full personal allowance. According to FPS Finance, the full allowance generally requires at least 75% of professional income to be taxable in Belgium.
Social contributions: the first major deduction
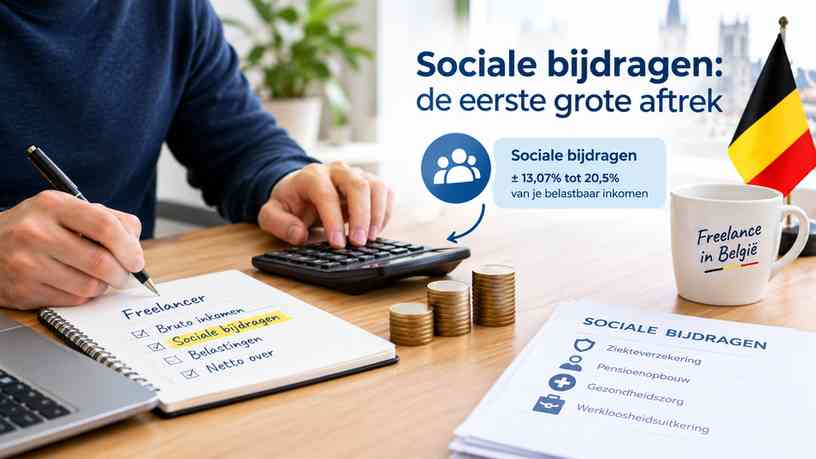
A self-employed person in a main occupation must join a recognised social-insurance fund and pay quarterly contributions. INASTI states that, for 2026, the standard rates are:
- 20.50% on professional income up to €75,024.54
- 14.16% on the portion between €75,024.54 and €110,562.42
- No percentage contribution above the upper ceiling
The calculation uses professional income after business expenses and losses. A minimum contribution applies, based on a minimum professional income of €17,374.08. Primostarters may qualify for reduced provisional contributions during their first four quarters.
Contributions are normally paid provisionally and later adjusted when the tax authorities establish your definitive income. The INASTI contribution guidance explains the system.
Social contributions fund rights such as healthcare, pension, incapacity benefits and family-related benefits. They are not simply an additional income tax.
Worked example: €60,000 annual freelance revenue
Consider an independent consultant living in Belgium with:
- Annual invoices excluding VAT: €60,000
- Deductible business expenses: €10,000
- Professional income before social contributions: €50,000
- Single person, no dependants
- Main-occupation sole proprietor
- Municipal surcharge assumed at 7%
Step 1: Social contributions
At 20.50% of €50,000:
€50,000 × 20.50% = €10,250
Step 2: Taxable professional income
Social contributions are generally deductible:
€50,000 – €10,250 = €39,750 taxable professional income
Step 3: Federal income tax estimate
Using the 2026 brackets:
- First €16,720 at 25% = €4,180
- Next €12,790 at 40% = €5,116
- Remaining €10,240 at 45% = €4,608
Gross tax: €13,904
The personal allowance reduces the final tax. A simplified calculation gives an estimated federal tax of approximately €11,100, before municipal surcharge.
Step 4: Municipal surcharge
At an assumed 7%:
€11,100 × 7% ≈ €777
Estimated result
| Item | Amount |
|---|---|
| Revenue excluding VAT | €60,000 |
| Business expenses | –€10,000 |
| Social contributions | –€10,250 |
| Estimated income tax and municipal surcharge | –€11,877 |
| Approximate amount remaining | €27,873 |
| Average monthly amount | about €2,323 |
This simplified example excludes pension savings, insurance, tax credits, family allowances, professional withholding, accounting costs and other personal adjustments. Actual net income may therefore be higher or lower.
The important lesson is that “€60,000 turnover” is not the same as €60,000 salary. In this example, only about 46% of invoiced revenue remains after operating expenses and estimated statutory deductions.
Which expenses can reduce your taxable income?
Belgian freelancers can generally deduct expenses that are necessary for earning professional income and properly documented. Common examples include:
- Laptop, monitor and business smartphone
- Software subscriptions and cloud services
- Professional insurance
- Accountant and legal fees
- Office rent or an eligible home-office share
- Business travel and qualifying transport costs
- Professional training
- Telecom and internet costs
- Marketing, website hosting and advertising
- Pension contributions within approved arrangements
The deduction may be limited when an item is used partly for private purposes. A €1,500 laptop used 70% for work is not automatically a €1,500 professional deduction.
Keep invoices, payment evidence and a clear business-use explanation. Tax authorities can reject expenses that appear excessive, private or unrelated to the activity.
VAT considerations for freelancers
Many Belgian freelancers must register for VAT and charge VAT on taxable services. VAT is separate from income tax and should not be treated as spendable revenue.
Small businesses with annual Belgian turnover not exceeding €25,000 may qualify for the small-business VAT exemption. Under this scheme, you generally do not charge VAT, but you also cannot recover input VAT on purchases. Registration and administrative obligations can still apply. Check the current conditions with FPS Finance.
For cross-border services, place-of-supply and reverse-charge rules can change how VAT appears on your invoice. An Indian client, Belgian client and EU business client may each require different treatment.
Sole proprietor or SRL/BV company?
A sole proprietorship is inexpensive and straightforward, but profits are taxed progressively up to 50%, plus municipal tax and social contributions.
An SRL/BV is a separate legal entity. The company pays corporate tax, and you may receive a salary, dividends or benefits. This can improve tax planning at higher profit levels, but it adds:
- Incorporation and accounting costs
- Annual company obligations
- Payroll administration
- Corporate tax filings
- Restrictions on withdrawing company cash
- Possible director remuneration requirements
A company is not automatically more tax-efficient. If you need to withdraw nearly all profits for living costs, the combined company and personal taxes may reduce the advantage. Compare both structures using projected profit, expenses, salary needs and long-term plans.
Main occupation versus side activity
If freelancing is your main occupation, you pay the full self-employed social-contribution system and minimum quarterly contributions.
If you freelance alongside qualifying employment, you may register as a secondary-occupation self-employed person. The same legal and administrative duties generally still apply, but social contributions can be reduced or eliminated at low income levels, depending on the applicable threshold.
Your employment salary also uses part of the lower tax brackets. As a result, side-business profit may be taxed at a higher marginal rate than expected.
What Indian freelancers should consider
Indian citizens working physically from Belgium may become Belgian tax residents depending on domicile, residence and personal circumstances. Residence, treaty rules and the location where services are actually performed are critical.
If you live in India and invoice Belgian customers remotely, Belgian VAT or withholding questions may still arise, but your personal income-tax position will usually be analysed under Indian residence rules and the Belgium–India tax treaty. Do not assume that a Belgian client automatically makes your income taxable in Belgium.
Before signing a contract, clarify:
- Where you are tax resident
- Whether you need Belgian self-employed registration
- Which country receives social contributions
- Whether VAT or reverse charge applies
- Whether the contract risks being viewed as false self-employment
- How currency conversion and foreign remittances are reported in India
A Belgian accountant working with international clients and an Indian Chartered Accountant can prevent expensive double-tax mistakes.
Practical ways to avoid a year-end tax shock
Set aside money from every invoice rather than waiting for the annual assessment. For many sole proprietors, reserving around 35% to 45% of profit for tax and social contributions is a cautious starting point, although high earners may need more.
Also:
- Pay provisional social contributions on an updated income estimate
- Track deductible expenses monthly
- Separate VAT money from operating cash
- Keep a quarterly profit forecast
- Consider advance tax payments to reduce late-payment increases
- Review pension and insurance planning annually
Frequently asked questions
What is the average tax burden for a freelancer in Belgium?
There is no single percentage. Combining social contributions, progressive income tax and municipal surcharge, many full-time sole proprietors experience an effective burden of roughly 35% to 50% of profit, before personal deductions and family benefits.
Is VAT included in my net freelancer income?
No. VAT collected from customers normally belongs to the tax authorities, after eligible input-VAT deductions. Calculate personal net income from revenue excluding VAT.
Can I deduct my laptop and smartphone?
Usually, the professional-use portion may be deductible when the purchase is genuinely connected to your work and supported by documentation. Private use can reduce the deductible percentage.
Are social contributions deductible in Belgium?
Social contributions are generally deductible when calculating taxable professional income, but they must be correctly paid and recorded through the social-insurance system.
Should an Indian freelancer create a Belgian company?
Not automatically. The answer depends on residence, expected profit, liability, salary requirements, administrative costs and cross-border tax rules. Obtain advice before incorporation.
Final takeaway
The Belgian freelancer tax burden is substantial, but it is predictable when you separate turnover, expenses, social contributions, income tax and VAT. For a sole proprietor, the realistic question is not “How much did I invoice?” but “What remains after documented costs and statutory deductions?”
Use the 2026 brackets and INASTI rates as planning references, maintain a cash reserve and obtain personalised advice before choosing between sole proprietorship and an SRL/BV structure.